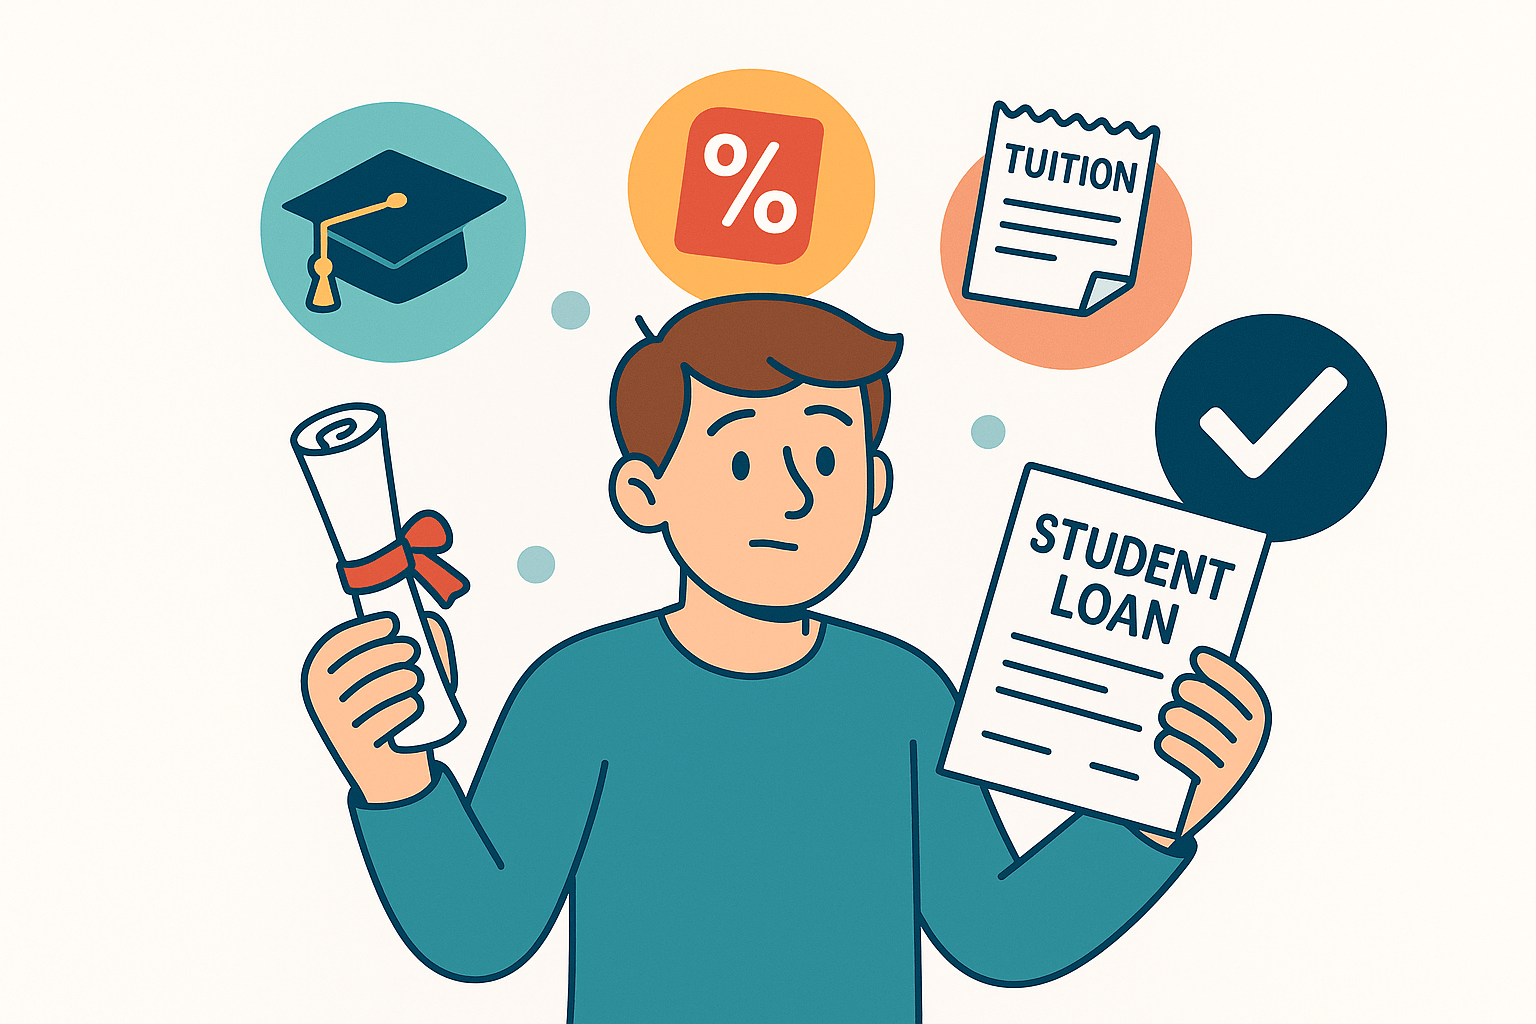
School is expensive. Whether you’re still studying or paying off those loans, you may have heard about tax breaks for education costs. But here’s where people get confused: student loan deductions and tuition deductions aren’t the same thing.
Let’s sort it out.
Student Loan Interest Deduction
This one’s for after graduation.
- You can deduct interest you paid on qualifying student loans.
- It applies even if you don’t itemize your deductions.
- Income limits may apply (higher earners may not qualify).
Think of it as: relief while you’re paying down loans.
Tuition & Education Credits
This one’s for while you (or your dependent) are in school.
- Covers tuition and certain required fees.
- Usually claimed through education tax credits like the American Opportunity Credit or Lifetime Learning Credit.
- Credits reduce your tax bill dollar-for-dollar, which can be more valuable than a deduction.
Think of it as: help while you’re still paying for school.
Quick Comparison
| Student Loan Interest Deduction | Tuition/Education Credits | |
|---|---|---|
| Applies to | Loan interest after school | Tuition/fees while in school |
| Type | Deduction (lowers taxable income) | Credit (lowers tax owed) |
| Who can claim | Borrower repaying student loans | Student or parent paying tuition |
Bottom Line
If you’re paying off loans, you may qualify for the student loan interest deduction. If you’re still in school (or paying for a dependent’s tuition), you may benefit from education credits instead.
👉 We’ll help you figure out which education tax breaks you qualify for. Book in 2 minutes: makeadultingeasier.com/book
Disclaimer: General information only — confirm with current IRS guidance or a tax professional.